Summary
Opening a business bank account in Dubai requires a valid trade license, proof of your registered office, shareholder and signatory identification, and a clear picture of your business activity and expected transaction volumes. Traditional banks typically take one to four weeks and may require a minimum balance of AED 50,000 or more, while digital banks like Wio and Mbank can approve simple applications in days with little or no minimum balance. This guide covers the full process, costs, and the mistakes that most often cause delays.
Every registered company in the UAE needs a corporate bank account to operate legally, pay staff, receive customer payments, and file VAT returns with traceable records. Setting this up correctly is one of the final practical steps after company formation in Dubai, and it sounds like a formality, but it’s one of the steps that catches new business owners off guard: banks in Dubai run detailed compliance checks on every applicant, and an incomplete or poorly prepared application is the single most common reason accounts get delayed or declined. This guide walks through exactly what’s required, how long it realistically takes, what different banks expect, and how to avoid the mistakes that send applications back to square one.
Why You Need a Business Bank Account in Dubai
A personal account cannot legally be used for business transactions in the UAE, and most clients and government portals won’t transact with a company that doesn’t have one. A registered corporate account is required to:
- Receive payments from clients and issue refunds through a traceable, business-registered channel
- Pay staff salaries through the UAE’s Wage Protection System
- Register for and file VAT with the Federal Tax Authority
- Apply for or renew a trade license in many free zones and with the DED
- Build a financial track record that supports future loan or credit facility applications
Skipping this step, or operating on a personal account instead, creates compliance exposure that most business owners only discover during their first audit or bank review.
Types of Business Bank Accounts in Dubai
Your company structure determines which accounts you’re eligible for and how the bank will assess you.
Mainland Company Accounts
Companies licensed by Dubai’s Department of Economic Development can open accounts with any UAE bank and generally face the most straightforward process, since mainland licenses allow trading directly across the UAE and with government entities.
Free Zone Company Accounts
Free zone companies can open accounts with most UAE banks too, though some banks scrutinise free zone activity types more closely, particularly for consulting, trading, or crypto-adjacent businesses. Many free zones, including IFZA, now have direct banking partnerships with digital banks like Wio, which can shorten the process considerably for their license holders.
Offshore Company Accounts
Offshore companies (unable to trade within the UAE itself) face the strictest scrutiny and the longest timelines, often one to three months, since banks apply enhanced due diligence to entities with no local trading activity.
Traditional Bank vs Digital Bank Accounts
This is now one of the biggest decision points. Traditional banks such as Emirates NBD, Mashreq, ADCB, RAKBank, FAB, and Dubai Islamic Bank offer full-service corporate banking, wider branch and ATM networks, and trade finance facilities, but usually require higher minimum balances and a longer approval process. Digital-only banks such as Wio Bank and Mbank have grown quickly in the UAE specifically by removing that friction: some offer account opening in under 48 hours with zero minimum balance for straightforward SME applications, though they’re a better fit for companies with simple banking needs than for those requiring trade finance or large multi-currency operations.
Best Banks for a Business Bank Account in Dubai
There’s no single “best” bank, the right choice depends on your company’s size, activity, and how you plan to bank day to day.
- Emirates NBD and Mashreq are frequently cited as among the more accessible traditional banks for SMEs, with established digital business banking platforms alongside branch access.
- ADCB and RAKBank are well regarded for SME-focused service and are commonly used by free zone companies.
- First Abu Dhabi Bank (FAB) and Dubai Islamic Bank suit businesses that want a full-service relationship, including trade finance and, for DIB, Sharia-compliant banking.
- HSBC and Standard Chartered run dedicated international desks, which can be useful for foreign-owned companies or those with significant cross-border banking needs.
- Wio Bank and Mbank represent the digital-first end of the market, built specifically around fast, largely remote onboarding for SMEs with straightforward banking needs.
Whichever you choose, ask directly about the minimum balance for your specific business size, monthly fees, and how the bank handles the KYC review for your particular activity type before submitting a full application.
Documents Required to Open a Business Bank Account
All UAE banks operate under the compliance framework set by the Central Bank of the UAE, so requirements are broadly consistent across institutions, though the exact checklist varies slightly by bank and company type. Almost every bank will ask for:
- A valid trade license (mainland or free zone)
- Memorandum of Association (MOA) and Articles of Association, where applicable
- Passport and Emirates ID copies for all shareholders, directors, and authorised signatories, so it’s worth confirming your Emirates ID status is active and not close to expiry before you apply
- Proof of your registered office: an Ejari certificate for mainland companies, or a free zone tenancy or flexi-desk certificate for free zone companies
- A completed bank application form and specimen signatures
- A business plan or company profile describing your activity, expected transaction volumes, and key clients or markets
- Six months of bank statements if you already operate an account elsewhere
- Source-of-funds documentation for shareholders, especially for higher-risk activities or larger expected deposits
Foreign companies opening a UAE branch account face an additional layer: their home-country incorporation documents typically need to be legalised through the UAE embassy in their country of registration and then attested by the UAE Ministry of Foreign Affairs, a process that can take several weeks on its own and is worth starting early.
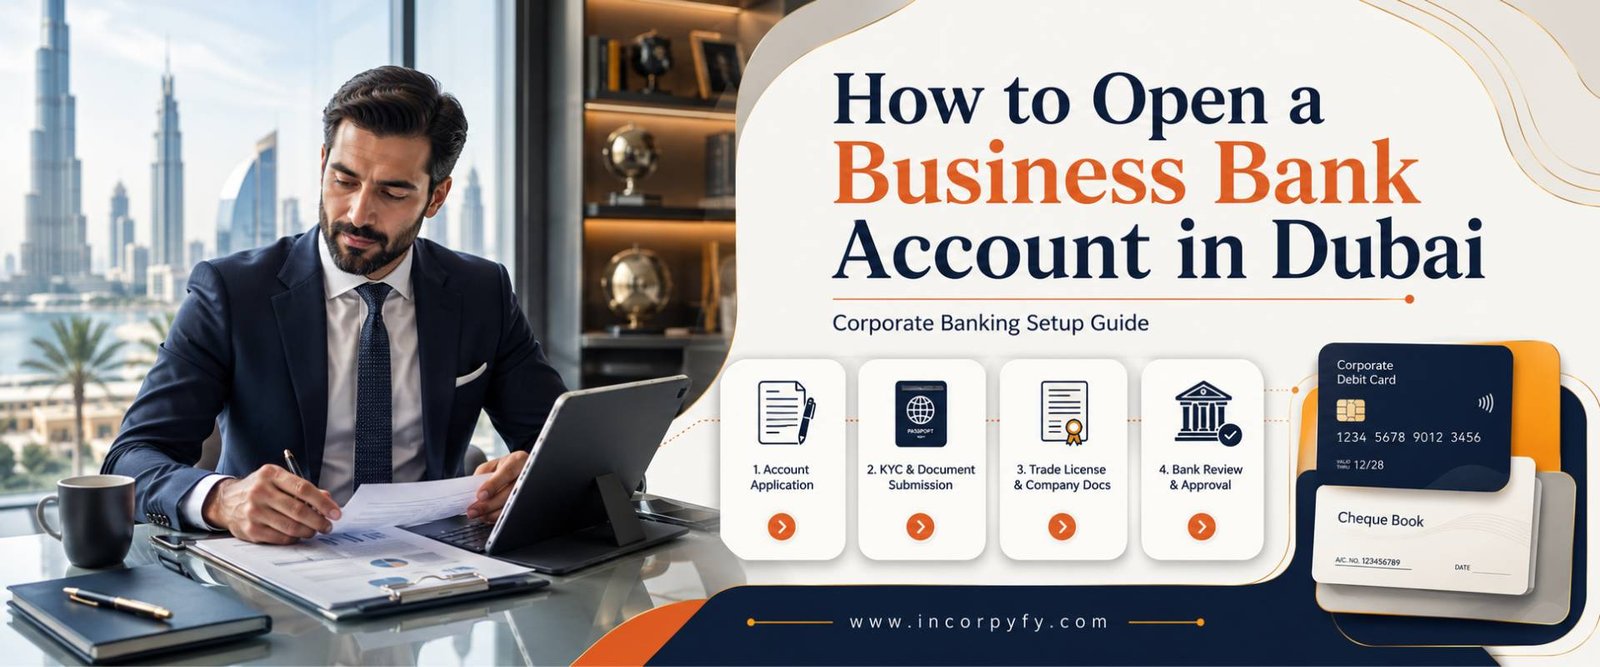
Step-by-Step Process to Open a Business Bank Account in Dubai
- Confirm your company structure and license are finalised. Banks won’t open an account against a pending license application.
- Choose your bank. Compare minimum balance requirements, monthly and transaction fees, international transfer capability, and whether you need a digital-only account or full-service corporate banking with trade finance.
- Gather your full document set before applying rather than submitting a partial file. Missing documents are the most common reason applications sit unprocessed for weeks.
- Submit your application, either at a branch, through the bank’s online business banking portal, or via video call for some digital banks.
- Complete KYC and compliance review. Expect questions about your business model, expected clients, transaction volumes, and source of funds. Some banks conduct a site visit or a call with the general manager or majority shareholder.
- Receive approval and fund the account. Once approved, you’ll deposit your opening balance and receive your IBAN, at which point the account is live for transactions.
Timeline and Cost to Open a Business Bank Account in Dubai
For a straightforward mainland or free zone company with clean documentation, most traditional banks approve applications within one to four weeks. Digital banks can move much faster, sometimes within a few business days, for simple SME applications. Offshore companies and foreign branch accounts should budget one to three months given the additional legalisation and enhanced due diligence involved.
Minimum balance requirements vary widely and are one of the most important factors in choosing a bank:
| Account type | Typical minimum balance | Notes |
|---|---|---|
| Traditional bank, standard tier | AED 50,000+ | Common baseline at major UAE banks |
| Traditional bank, relationship-managed tier | AED 250,000+ | Applies where a dedicated relationship manager is assigned |
| Digital-first business account | AED 0 to AED 10,000 | Wio, Mbank, and similar providers, best for simple SME needs |
Beyond the minimum balance, budget for monthly account fees, transaction and transfer charges, and, if your incorporation documents originate outside the UAE, the cost of legalisation and attestation, which can run into the thousands of dirhams per document.
Common Reasons a Business Bank Account Application Gets Rejected
- Incomplete documentation. This is consistently the leading cause of delay across every bank, not a one-off issue with any single institution.
- Unclear business activity. Vague descriptions of what the company actually does, or activity that doesn’t match the trade license, trigger extra scrutiny.
- Mismatched information across documents. Names, addresses, or shareholder details that don’t match exactly between the trade license, MOA, and identification documents cause automatic delays.
- High-risk or poorly understood activity types. Certain sectors, cryptocurrency, international trading with limited paper trail, or cash-intensive businesses, face additional compliance layers regardless of which bank is chosen. Crypto businesses in particular should plan for this well before applying, our guide to getting a crypto license in Dubai covers the banking relationship side of that process in more detail.
- No clear source of funds. Banks increasingly expect a straightforward explanation of where initial capital and expected deposits are coming from, not just a number on a form.
Tips to Get Your Business Bank Account Approved Faster
- Prepare every document in the checklist above before your first meeting, rather than submitting and completing the file over several visits.
- Be specific about your business activity, expected clients, and transaction volumes rather than giving generic answers.
- If your business has an existing banking history elsewhere, bring six months of statements even if not explicitly requested, it speeds up the credibility assessment considerably.
- Match your bank choice to your actual needs: a company that only needs to invoice a handful of clients each month doesn’t need the overhead of a relationship-managed account with a AED 250,000 minimum balance.
- Consider a digital bank for a straightforward SME setup, and reserve traditional banks for businesses that need trade finance, large multi-currency operations, or an extensive branch network.
Opening a Business Bank Account as a Non-Resident or Foreign Company
Non-residents can open a UAE company account without holding a UAE residency visa, provided the business itself is properly registered locally, though expect a longer process and enhanced due diligence. Banks with dedicated international or non-resident desks, larger UAE banks and some international names with a UAE presence, are generally better equipped to handle these applications than smaller institutions. Budget extra time for document legalisation from your home country, and expect the bank to ask more detailed questions about the ultimate beneficial owners of the business.
How Incorpyfy Can Help
Choosing the right bank, assembling a compliant document file, and answering a bank’s compliance questions correctly the first time is exactly the kind of detail that determines whether an account opens in two weeks or gets stuck for two months. At Incorpyfy, our team supports clients through every stage of business setup in Dubai, including preparing bank-ready documentation, matching businesses to the right banking partner, and managing the process from application to a fully funded, operational account.
Conclusion
A business bank account in Dubai is not a rubber-stamp process, but it’s a manageable one when you understand what each bank is actually checking for. Confirm your company structure, prepare a complete and consistent document file, be specific about your business activity and source of funds, and choose a bank that matches your actual transaction needs rather than defaulting to the biggest name. Businesses that prepare this way typically move through approval in weeks rather than months.
FAQs
How long does it take to open a business bank account in Dubai?
Most straightforward mainland or free zone applications are approved within one to four weeks at traditional banks, and within a few business days at digital-first banks. Offshore and foreign branch accounts can take one to three months.
What is the minimum balance for a corporate bank account in Dubai?
It depends on the bank and tier. Traditional banks commonly require AED 50,000 or more, with relationship-managed accounts requiring AED 250,000 or above. Several digital banks now offer accounts with no minimum balance for qualifying SMEs.
Can a non-resident open a business bank account in Dubai?
Yes, provided the company is properly registered in the UAE. Non-residents should expect enhanced due diligence and should prepare legalised home-country documents in advance.
What documents are needed to open a business bank account in the UAE?
At minimum: a valid trade license, MOA/AOA where applicable, passport and Emirates ID copies for shareholders and signatories, proof of your registered office, and a business plan or company profile describing your activity and expected transaction volumes.
Is it faster to open an account with a digital bank than a traditional bank?
Usually, yes, for straightforward SME applications. Digital banks like Wio and Mbank have built their process around fast, largely remote onboarding, though traditional banks remain better suited to businesses that need trade finance or extensive multi-currency operations.
Why do business bank account applications get rejected in Dubai?
The most common reasons are incomplete documentation, business activity that doesn’t clearly match the trade license, mismatched details across documents, and an unclear explanation of the source of funds.
Does a free zone company need a different bank account process than a mainland company?
The core document requirements are similar, but free zone companies typically provide a free zone tenancy or flexi-desk certificate instead of an Ejari certificate, and some banks assess certain free zone activity types more closely than mainland equivalents.